

How Blockchain is solving the Problem of Double-Spending in the Finance Sector?
 Toshendra Kumar Sharma
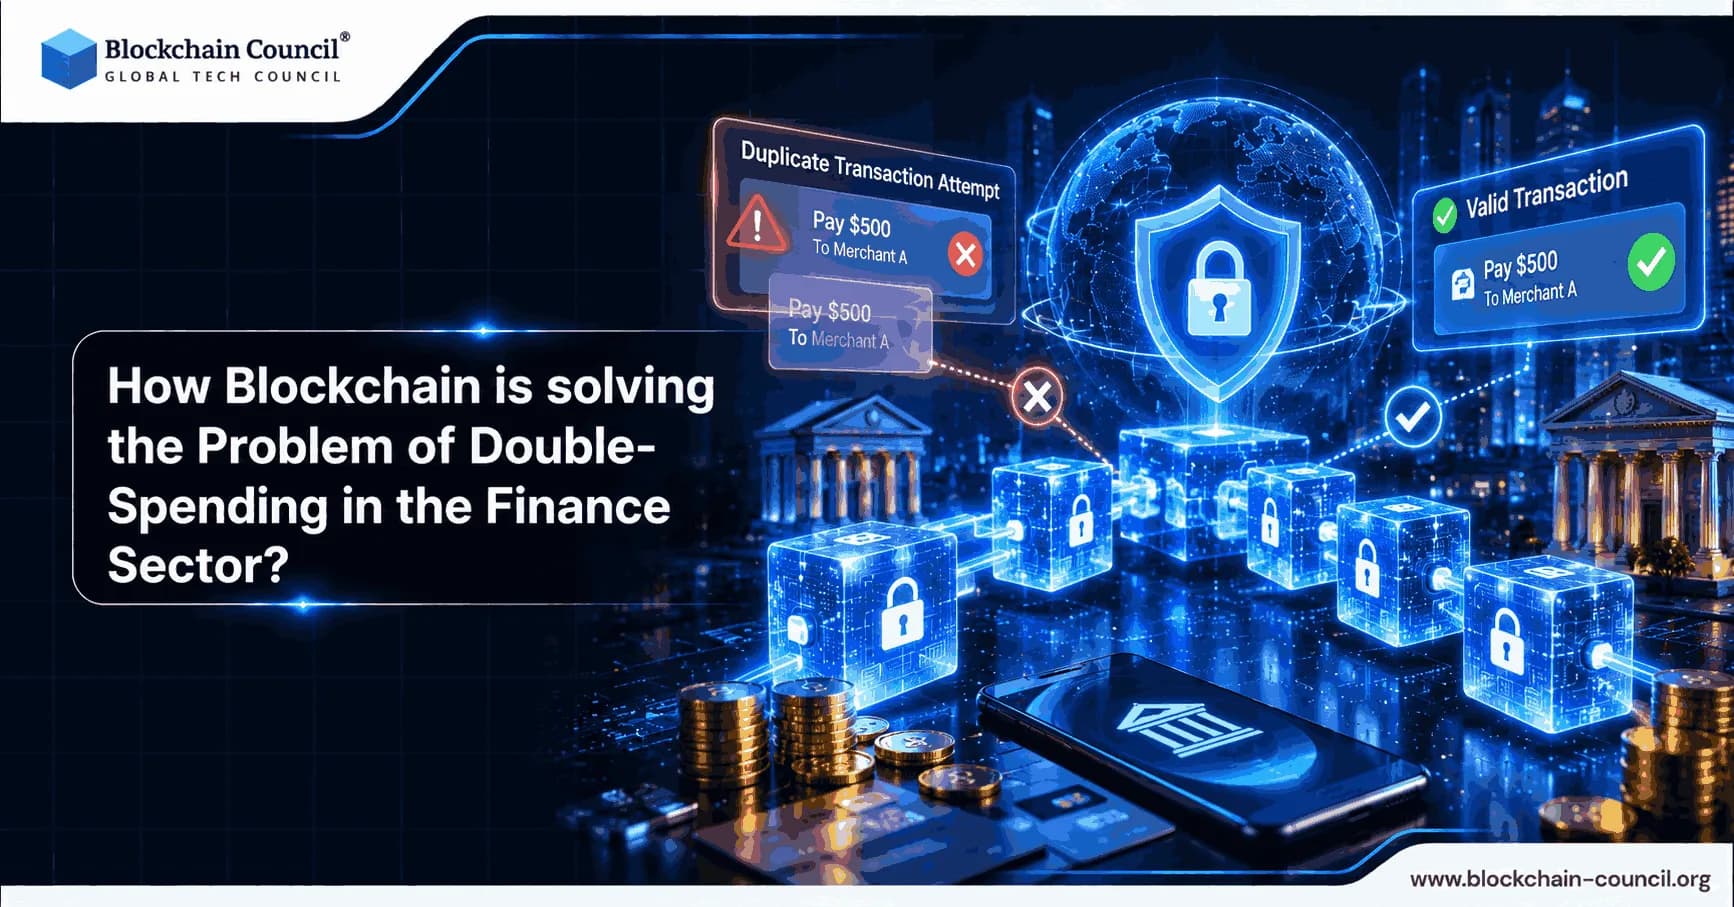
Imagine paying for a coffee with a $10 bill. Once you hand it over, you no longer have it. Now imagine that money was just a file on your phone. What stops you from copying it and paying twice? This is the double-spending problem, and for years it blocked the idea of true digital cash. Today, how blockchain solves double spending is one of the most important ideas in modern finance, because it lets people move value online without a bank checking every payment. If you want to understand this technology from the ground up, the Certified Blockchain Expert program is a solid place to start.
This guide explains the problem, the solution, the risks, and the real-world impact, in plain language for beginners and with enough depth for professionals.
What Is Double-Spending?
Double-spending means using the same unit of digital money more than once. Digital files are easy to copy, so without a safeguard, a person could send the same coin to two different people and both payments could look valid.
Before blockchain, the standard fix was a trusted middleman. A bank keeps a central ledger, subtracts money from your account when you pay, and refuses a second payment if the funds are gone. That works, but it requires trust in one organization, adds fees, and can be slow, especially across borders.
Blockchain offers a different answer. Instead of one trusted record keeper, thousands of computers keep the same ledger and agree on its contents.
How Blockchain Solves Double Spending, Step by Step
Anyone who builds financial applications needs to understand these mechanics in detail, because the design choices affect safety. Practical training such as the Certified Blockchain Developer course teaches how to build and test blockchain applications with these protections in mind. Here is how the system works.
A Shared Ledger Everyone Can Check
Every payment is broadcast to the network, and nodes (computers running the software) check it against the ledger. If a coin has already been spent, the second transaction is rejected as invalid. Because every node can verify the history for itself, no single bank is needed to say "this money is already gone."
Consensus Decides Which Payment Counts
Sometimes two conflicting transactions reach the network at about the same time. The network needs a rule to pick one. This rule is called consensus.
Proof of work (Bitcoin): Miners compete to add the next block of transactions by solving a hard puzzle. The longest chain of blocks wins, and the transaction on it counts.
Proof of stake (Ethereum): Validators lock up coins as a deposit and vote on valid blocks. Dishonest behavior can lead to a penalty called slashing, where part of the deposit is destroyed.
In both systems, the conflicting payment simply loses and never becomes part of the official history.
Confirmations and Finality
Each new block added on top of a payment makes it harder to reverse. Bitcoin blocks arrive about every 10 minutes, and a common rule of thumb is to wait for six confirmations, roughly an hour, before treating a large payment as settled.
Ethereum uses a concept called finality. After about two epochs, which is roughly 12.8 minutes, a block is considered finalized. Reversing it would require destroying at least one-third of all staked ETH, which would cost tens of billions of dollars. That is why finality is called economic: the price of cheating is written into the rules.
Types of Double-Spending Attacks
Blockchain makes double-spending very difficult, but attackers have tried several tricks. Knowing them helps explain why waiting for confirmations matters.
Race Attack
An attacker sends two conflicting transactions at nearly the same moment. One goes to a merchant, and the other goes to the attacker's own address. If the merchant hands over goods before the payment is confirmed, the attacker may end up with both the goods and the coins. The simple defense is to wait for confirmation.
Finney Attack
Named after early Bitcoin developer Hal Finney, this attack needs a miner. The attacker secretly mines a block containing a payment to themselves, then spends the same coins at a merchant who accepts an unconfirmed payment, and finally releases the secret block. It also only works against merchants who do not wait for confirmation.
51 Percent Attack
If one party controls more than half of a network's mining power, they can secretly build a longer chain, rewrite recent history, and reverse their own payments. This attack can work even after several confirmations, which makes it the most serious threat. It is expensive and very hard on large networks, and far more realistic on small ones.
Building defenses against these attacks involves networking, cybersecurity, cloud systems, and monitoring. That is why many finance and technology professionals pair blockchain study with a broader Tech Certification, which covers the wider technology stack that secure financial systems depend on.
Real-World Cases
Real attacks show the difference between large and small networks:
Bitcoin Gold (2018): An attacker took control of the majority of the network's mining power and double-spent coins worth more than $18 million, according to widely cited reports.
Ethereum Classic (2019): A series of 51 percent attacks led to double-spending reported at roughly $1.1 million, and further attacks followed in 2020.
Both were smaller networks with less total mining power. As far as public records show, the largest networks, Bitcoin and Ethereum, have not suffered a successful attack of this type. The lesson for finance is clear: the security of a blockchain depends heavily on how many honest participants protect it.
How the Finance Sector Uses These Protections
The double-spending fix is what makes blockchain useful for real money:
Faster settlement. Traditional securities trades can take a day or more to settle, and even the US moved to a one-day cycle only in 2024. Blockchain-based settlement can compress this, since ownership changes are recorded and finalized on the shared ledger itself.
Cross-border payments. Moving money abroad often involves several banks, each keeping its own records and charging fees. A shared ledger reduces the need for repeated reconciliation.
Stablecoins. These tokens are designed to hold a steady value, usually one dollar. A recent industry report put their total market above $315 billion in September 2026, and their usefulness depends on trust that a token cannot be spent twice.
Tokenized assets. Bonds, funds, and other assets can be represented as tokens. Tokenized US Treasuries were reported at around $11 billion in early 2026. Each token must be unique and traceable, which is exactly what double-spending protection provides.
Smart contracts. Automated agreements for lending, trade finance, and payments rely on a ledger that cannot be quietly altered.
Limits and Challenges
Blockchain is not a magic shield, and finance teams should be aware of the following:
Waiting time. Strong protection takes confirmations. Bitcoin may need about an hour for high confidence, and Ethereum about 13 minutes for finality. Some businesses use faster methods but accept more risk.
Small networks are weaker. A chain with little mining power or stake is easier to attack.
Scalability. Large public networks handle a limited number of transactions per second, which can cause congestion and high fees.
Other attack paths. Double-spending protection does not stop phishing, stolen keys, or smart contract bugs, which cause many real losses.
Regulation and compliance. Banks and payment firms must follow anti-money-laundering and consumer protection rules, which vary by country.
Practical Tips for Finance Teams
If you are exploring blockchain payments, keep these steps in mind:
Choose a well-secured network. Larger networks with more mining power or stake are harder to attack.
Never accept unconfirmed payments for valuable goods. Match the number of confirmations to the value at risk.
Understand finality. Know exactly when a transaction is irreversible on your chosen chain.
Monitor the network. Watch for unusual reorganizations of the chain and for sudden changes in mining power.
Pilot first. Test with small amounts and trusted partners before moving large flows.
Technology only creates value when customers and colleagues understand it. Financial teams must explain settlement times, safety, and fees in simple words, and a Marketing Certification can help professionals communicate these points clearly and build trust with users.
Conclusion
Double-spending was once the biggest obstacle to digital money. Understanding how blockchain solves double spending shows why the idea changed finance. A shared ledger, a consensus rule, and confirmations or finality work together so that a coin can be spent only once, without a central bank checking every payment. The system is not perfect: small networks can be attacked, and users must wait for confirmations to be safe. Still, for faster settlement, cross-border payments, stablecoins, and tokenized assets, this protection is the foundation that makes digital finance trustworthy.
FAQs
1. What is the double-spending problem in finance?
Double-spending occurs when the same digital asset is used in two or more transactions. Unlike physical cash, digital information can be copied, so a system needs a reliable way to determine which transaction is valid.
2. How does blockchain solve the double-spending problem?
Blockchain maintains a shared ledger of transactions and uses cryptography and consensus to determine which transactions are valid. Once a transaction is accepted into the ledger, conflicting transactions that attempt to spend the same asset are rejected according to the network's rules.
3. Why is double-spending a major issue for digital finance?
Digital assets can be represented as information that can potentially be copied or submitted multiple times. Without a reliable transaction history and validation mechanism, users could attempt to transfer the same asset to multiple recipients.
4. How does a blockchain ledger prevent double-spending?
The ledger records the history of asset transfers and allows the network to determine whether an asset has already been spent. Participants can use the shared transaction history to verify ownership and identify conflicting transactions.
5. What role does consensus play in preventing double-spending?
Consensus allows network participants to agree on the valid state of the ledger. When conflicting transactions appear, the consensus rules determine which transaction becomes part of the accepted transaction history.
6. How does cryptography help prevent double-spending?
Digital signatures allow participants to verify that a transaction was authorized by the holder of the relevant private key. Cryptographic hashes also help link and protect records within a blockchain, supporting the integrity of the transaction history.
7. Can blockchain prevent someone from submitting two transactions at the same time?
Blockchain networks can receive conflicting transactions, including transactions that attempt to spend the same asset. The network's validation and consensus rules determine which transaction can become part of the accepted ledger, rather than allowing both conflicting transactions to represent valid final transfers.
8. What happens when two transactions try to spend the same cryptocurrency?
The network evaluates the transactions according to its protocol rules. One transaction may be accepted into the blockchain while the conflicting transaction is rejected or becomes invalid once the relevant transaction is confirmed.
9. How does Bitcoin prevent double-spending?
Bitcoin uses a peer-to-peer network, digital signatures, transaction broadcasting, and proof-of-work consensus to establish a shared chronological transaction history. The blockchain provides a record that allows the network to determine which conflicting transaction is accepted.
10. Does blockchain completely eliminate double-spending?
Blockchain protocols are specifically designed to prevent the same asset from being validly spent twice, but the protection depends on the security and rules of the particular network. Unconfirmed transactions, attacks, implementation errors, or other weaknesses can create risks that users and financial systems must consider.
11. What is the role of transaction confirmation in preventing double-spending?
Confirmation means that a transaction has been included in the blockchain and accepted by the network. Additional confirmations can make a reversal increasingly difficult on systems such as Bitcoin.
12. How can blockchain prevent double-spending without a central authority?
A distributed blockchain can replace a single central ledger operator with a network of participants that validate transactions according to shared rules. Consensus allows these participants to agree on the accepted transaction history.
13. How does blockchain benefit banks and financial institutions in preventing double-spending?
A shared ledger can help participating institutions maintain a consistent view of transactions and asset ownership. This can reduce reconciliation problems between separate databases and support more efficient transfer and settlement processes.
14. Can blockchain prevent double-spending in digital payments?
Yes, blockchain-based payment systems can use distributed ledgers and consensus to prevent conflicting transfers of the same digital asset. The specific approach depends on whether the network is public, permissioned, or operated by a group of financial institutions.
15. Can smart contracts help prevent double-spending?
Smart contracts can enforce predefined rules governing digital assets and transactions. When combined with an underlying blockchain's consensus mechanism, they can help ensure that an asset or token is transferred according to the system's defined rules.
16. Is blockchain the only solution to the double-spending problem?
No. Traditional financial systems prevent double-spending through centralized ledgers and trusted intermediaries such as banks and payment processors. Blockchain provides an alternative approach based on distributed record-keeping and consensus.
17. What are the limitations of blockchain in preventing double-spending?
Blockchain systems can face challenges involving scalability, transaction speed, privacy, governance, and consensus security. The BIS notes that different blockchain designs involve trade-offs between decentralization, security, and scalability, and that these factors matter for financial applications.
18. Can a double-spending attack still happen on a blockchain?
A blockchain's consensus mechanism is designed to make conflicting transactions difficult to establish as valid simultaneously. However, certain attacks or network conditions can create temporary or attempted double-spending risks, particularly before sufficient transaction finality is achieved.
19. How can blockchain improve trust in digital financial transactions?
Blockchain can provide participants with a shared transaction history that can be independently verified according to the network's rules. This can reduce dependence on a single party to maintain the authoritative record, although financial systems still require governance, regulation, compliance, and operational controls.
20. What is the future of blockchain for preventing double-spending in finance?
Blockchain and other distributed ledger technologies may continue to support payments, settlement, tokenized assets, and financial market infrastructure. However, financial institutions are likely to use different forms of DLT depending on requirements for privacy, scalability, governance, compliance, and transaction finality.
Related Articles
View All
Blockchain
Blockchain in Banking and Finance: Use Cases, Benefits, and Future Trends
Explore blockchain in banking and finance, including payments, tokenization, custody, lending, trade finance, compliance, benefits, and future trends.

Blockchain
Why Blockchain Is the Future of Digital Trust, Finance, and Data Security
Blockchain is becoming core infrastructure for digital trust, finance, and data security through shared ledgers, stablecoins, smart contracts, and verifiable records.

Blockchain
Beyond Cryptocurrency: How Blockchain Is Transforming Real-World Industries
Explore how blockchain works beyond cryptocurrency in banking, supply chains, healthcare, tokenisation, CBDCs, and government, plus key challenges and career paths.
Trending Articles
The Role of Blockchain in Ethical AI Development
How blockchain technology is being used to promote transparency and accountability in artificial intelligence systems.
Top 5 DeFi Platforms
Explore the leading decentralized finance platforms and what makes each one unique in the evolving DeFi landscape.
How Blockchain Secures AI Data
Understand how blockchain technology is being applied to protect the integrity and security of AI training data.