

RWA Tokenization Compliance: Legal Requirements, Controls, and Best Practices
 Suyash Raizada
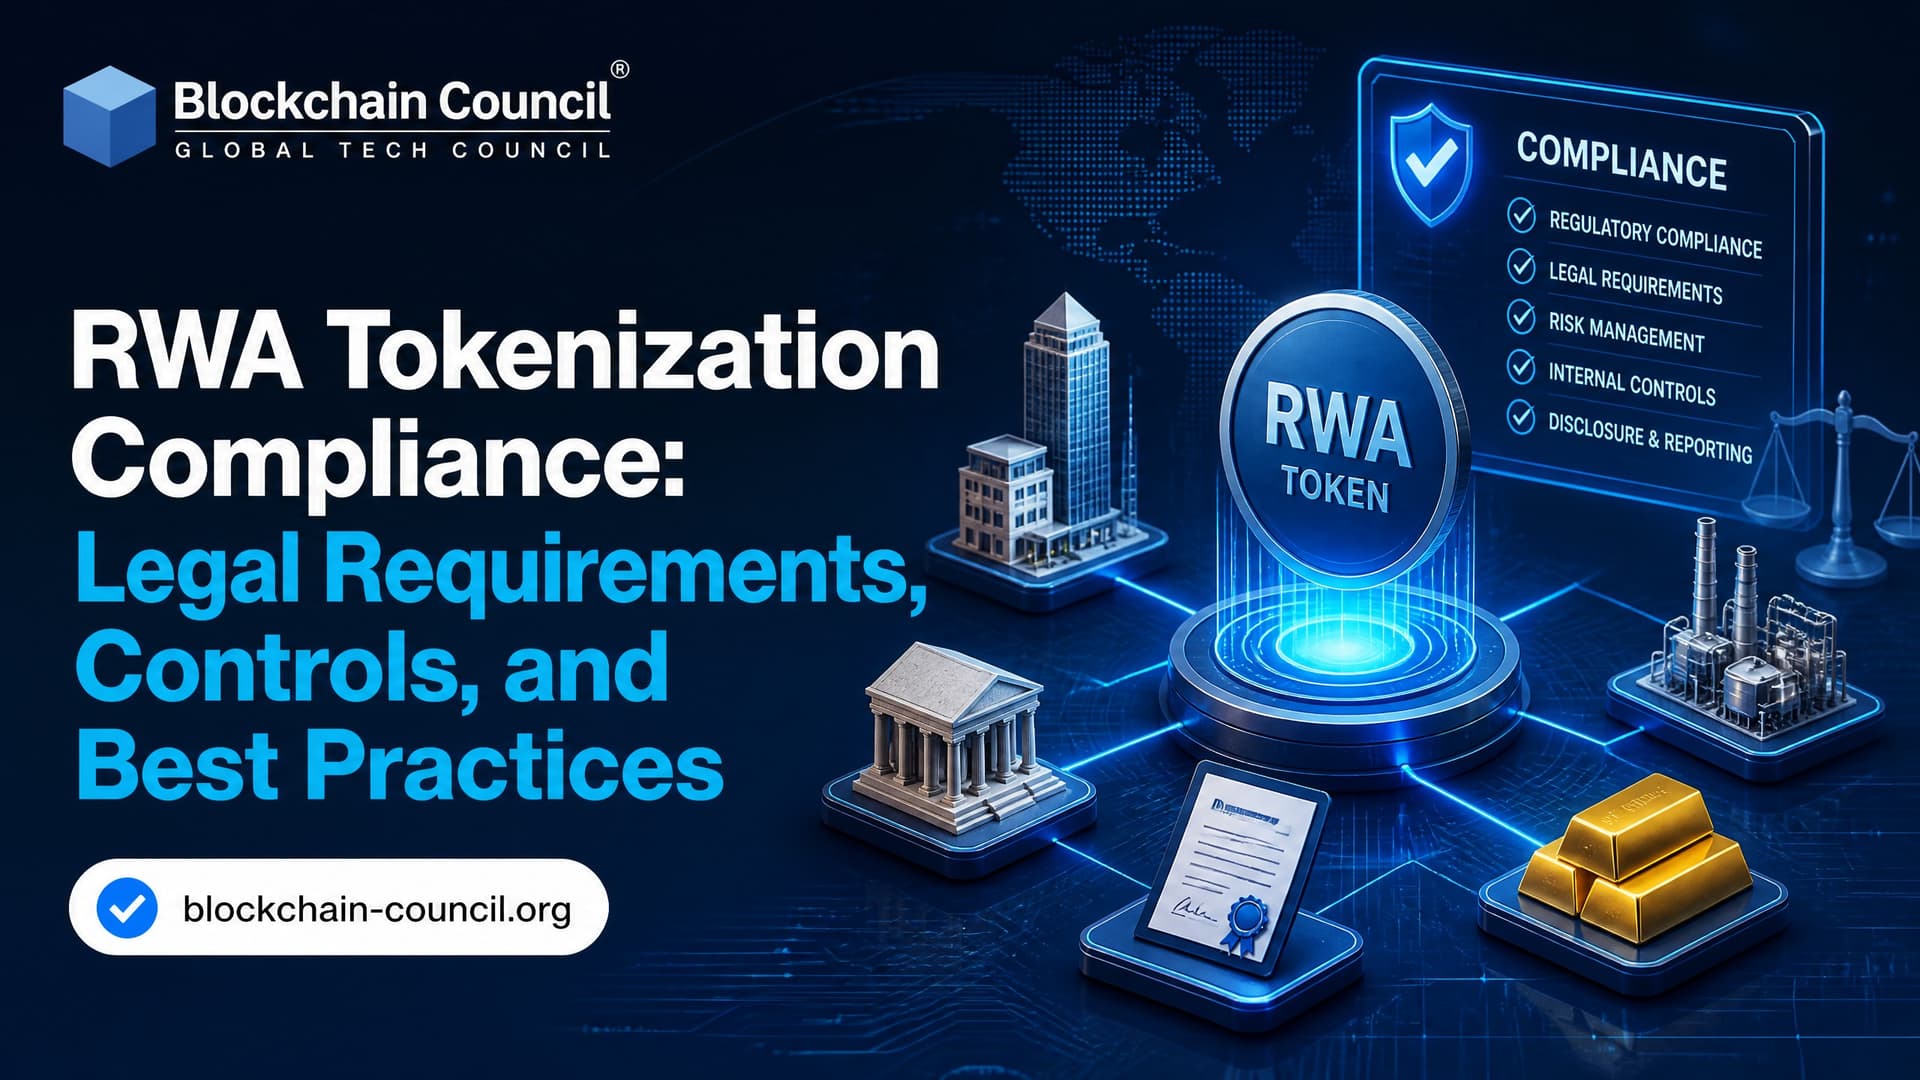
RWA tokenization compliance now looks much less like a crypto experiment and much more like regulated finance running on blockchain rails. If a token represents income, profit rights, fund interests, debt, real estate, commodities, or a claim on a pool of assets, assume securities, AML, investor protection, custody, and reporting rules apply until counsel proves otherwise. Anyone building or supervising these systems benefits from a structured grounding in the discipline, which is exactly what the Certified RWA Tokenization Expert credential is designed to provide.
That is not a conservative slogan. It is where the market has moved. Industry analyses put the tokenized real world asset market, excluding stablecoins, at roughly 15.2 billion dollars by December 2024 and above 24 billion dollars by mid 2025. Include stablecoins and the number is far larger, with stablecoins still dominating tokenized value. The signal is clear. Institutions are entering RWA tokenization, and they expect controls that legal, compliance, operations, and engineering teams can defend.

What RWA Tokenization Compliance Means
RWA tokenization compliance is the set of legal, technical, and governance controls that connect an on chain token to an enforceable off chain right. The token is not the whole product. The legal wrapper, issuer, custody arrangement, transfer rules, disclosures, and audit trail matter just as much.
For most serious projects, the compliance architecture should answer five questions:
What is the token legally? A security, fund unit, asset referenced token, debt instrument, commodity claim, or something else?
Who may hold it? Retail investors, accredited investors, qualified purchasers, institutions, or only residents of specific jurisdictions?
What backs it? Treasuries, private credit, real estate, commodities, invoices, art, or cash reserves?
Who safeguards the asset? A regulated custodian, trustee, broker dealer, fund administrator, or SPV?
How do regulators and auditors reconstruct events? Through registers, smart contract logs, transfer approvals, KYC records, and reporting data.
To be blunt, a token contract without these answers is just a database entry with a wallet interface. Since these questions increasingly overlap with how stablecoins, tokenized deposits, and other digital instruments are governed, many compliance professionals broaden this study with the Certified Digital Assets Expert program, which frames these different asset types within one connected compliance picture.
Legal Requirements by Jurisdiction
United States
The United States has no single RWA tokenization statute. The analysis depends on the asset, the rights attached, the marketing, the investor base, and the trading model. Tokens that convey profit rights, income rights, fractional interests, or exposure to a managed asset pool are commonly treated as securities under existing federal securities laws.
That means an issuer may need a registered offering or a valid exemption such as a private placement route. Platforms that arrange secondary trading may need broker dealer, alternative trading system, investment adviser, or transfer agent registrations depending on their role. AML, KYC, sanctions screening, suspicious activity monitoring, books and records, and customer protection rules stay relevant whether the token runs on Ethereum mainnet, a permissioned chain, or a private ledger.
The SEC's public engagement on tokenized securities has pointed in the same direction. Tokenized assets may fit into existing market infrastructure, but custody, segregation, customer protection, and trading rules do not disappear.
European Union and MiCA
In the European Union, MiCA creates a clearer route for many crypto assets, but it does not make RWA tokens unregulated. Tokens backed by or referencing assets such as commodities, real estate, or baskets of value may fall into the asset referenced token category. Issuers can face white paper, authorization, governance, capital, reserve, complaints handling, and custody obligations.
One common mistake is treating MiCA as a single passport for any tokenized asset. It is not. If the token is a financial instrument under MiFID II, securities law can still apply. Classification comes first, product design second.
Dubai, India, and Emerging Markets
Dubai's Virtual Assets Regulatory Authority has built a licensing model for virtual asset activity. RWA token issuers and platforms may need licenses, white papers, audits, minimum paid up capital, and ongoing compliance with conduct and prudential rules.
India and several emerging markets are still shaping their approach. SEBI has explored tokenized securities concepts, but until specific frameworks settle, firms should treat tokenized fund interests, real estate fractions, and income rights as regulated securities or collective investment schemes. That is the safer design assumption.
Core Controls for Compliant RWA Tokenization
Legal Structuring and SPV Design
Most compliant RWA models use a dedicated issuer or special purpose vehicle that holds the underlying asset and issues tokens representing beneficial interests. This isolates risk, defines insolvency treatment, and connects token balances to legal rights.
You also need a master off chain register. The blockchain can show transfers, but the legal register should document ownership, liens, corporate actions, redemptions, and dispute handling. Contracts should state how on chain records are treated as evidence, which law governs, and how errors get resolved.
AML, KYC, and Investor Eligibility
RWA tokens need identity controls. At minimum, implement:
Customer identity verification for individuals and entities.
Sanctions screening against relevant lists.
Risk scoring for geography, investor type, and transaction pattern.
Ongoing monitoring for suspicious activity.
Eligibility checks for accredited, professional, or qualified investor status where required.
A practical architecture stores sensitive identity documents off chain with a regulated verification provider, then places only an attestation or permission status on chain. Do not put passports, tax IDs, or beneficial ownership documents directly on a public blockchain. You will create a privacy problem that is hard to unwind.
Programmable Transfer Restrictions
Compliant token standards matter. ERC-1400 and ERC-3643 are widely discussed for security tokens because they support permissioned transfers, identity links, partitions, and regulatory controls. Newer proposals such as ERC-7518 aim to add more dynamic compliance primitives, including rule engines, jurisdiction checks, and forced transfer mechanics.
Useful controls include:
Whitelists for approved wallets.
Blacklists for sanctioned or blocked addresses.
Transfer caps by investor, country, or offering limit.
Partitions for different share classes or lockup periods.
Freeze and forced transfer functions for court orders, fraud response, or regulatory instructions.
A small practitioner detail. If your Solidity 0.8.x contract uses OpenZeppelin AccessControl, version 5.x changed the old revert string style. You may now see custom errors such as AccessControlUnauthorizedAccount instead of the older AccessControl: account is missing role message. That matters when your compliance operations team is testing pause, freeze, or forced transfer roles and still expects the older runbook screenshots.
Custody, Reconciliation, and Asset Servicing
RWA tokenization fails if the asset backing is vague. Use regulated custodians, trustees, fund administrators, or qualified asset servicers where the asset class requires it. For tokenized Treasuries, private credit, and fund units, custody and recordkeeping should match traditional market expectations.
Reconcile often. Daily is common for liquid financial assets. The on chain supply, investor register, custodian statement, bank account, reserve report, and issuer ledger should not drift. If they do, stop transfers until you understand the break.
Audit Trails and Reporting
Regulators and auditors need a clean path from legal approval to on chain event. Capture the full lifecycle:
Investor onboarding and eligibility approval.
Subscription documentation.
Token minting.
Transfers and failed transfers.
Distributions and corporate actions.
Redemptions and burns.
Freezes, overrides, and disputes.
Good audit design is boring. That is a compliment. It lets a supervisor reconstruct who approved what, when, under which rule, and against which legal document.
Common RWA Use Cases and Compliance Patterns
Tokenized Treasuries and Cash Equivalents
Tokenized US Treasuries have become one of the strongest institutional RWA categories. These products usually operate through regulated funds, broker dealers, transfer agents, or custodians, with tokens representing fund shares or beneficial interests. Expect securities rules, reserve reporting, investor eligibility checks, and tight redemption procedures.
Real Estate and Infrastructure
Real estate tokenization often uses an SPV that owns the property, with tokens representing fractional interests in that vehicle. Compliance is harder than the pitch decks suggest. Local land rules, tax, foreign ownership caps, mortgage restrictions, and title records may block simple free transferability.
Private Credit and Funds
Private credit tokenization is growing because distribution, reporting, and settlement improve with token rails. But the tokens usually represent fund interests or claims on loan pools. That means securities and fund regulation, not a casual NFT-style drop.
Commodities, Art, and Collectibles
For commodities and alternative assets, proof of reserve and custody are the weak points. A gold backed token needs credible vaulting, insurance, inspection, redemption rules, and reporting. An art backed token needs provenance, a valuation policy, storage, insurance, and dispute handling.
Best Practices Checklist
Classify first: Treat income, profit, or pooled asset tokens as regulated unless legal analysis says otherwise.
Map licenses: Separate issuance, custody, brokerage, trading, advisory, and asset servicing functions.
Use a proper issuer: Build SPVs or legal entities that match property, securities, tax, and insolvency rules.
Keep the legal register: Do not rely only on token balances.
Design KYC into transfers: Check eligibility before minting and before secondary transfers.
Use tested token standards: ERC-3643 or ERC-1400 will usually suit regulated assets better than a plain ERC-20.
Add emergency controls: Pause, freeze, and forced transfer powers should be documented, permissioned, logged, and limited.
Reconcile backing assets: Match on chain supply to off chain assets and liabilities.
Prepare for migration: Smart contracts, regulations, and custodians all change. Build an orderly upgrade plan.
Skills Teams Need for RWA Tokenization Compliance
RWA tokenization sits between law, finance, cybersecurity, and smart contract engineering. If you are building or supervising these systems, strengthen both the legal model and the technical implementation. Blockchain Council programs such as the Certified Blockchain Expert™ and Certified Smart Contract Developer™ give teams a shared vocabulary across compliance and engineering.
If your role is closer to risk, custody, or investigations, pair blockchain training with AML, cybersecurity, and digital asset governance skills. The best RWA teams are not made of Solidity developers alone. Professionals looking to broaden their technical capabilities across emerging technologies can also explore a Tech Certification aligned with their career goals.
Future-Ready Skills
As technology becomes increasingly important across industries, students need opportunities to develop future-ready skills early in their education. A Tech Olympiad can introduce students to areas such as artificial intelligence, coding, cybersecurity, robotics, and computational thinking while encouraging curiosity and continuous learning.
The Direction of Regulation
The next phase of RWA tokenization compliance will be less about proving that tokenization can work and more about proving that it can be supervised. MiCA is already shaping global thinking. US regulators continue to evaluate broker dealer custody, transfer agents, and alternative trading systems for tokenized securities. Emerging markets are watching tokenized securities, real estate, SME credit, and commodities closely.
Programmable compliance will improve, but do not outsource judgment to code. Smart contracts can block an ineligible transfer. They cannot decide whether your marketing deck created an unregistered public offering.
Your next step: build a compliance map before writing token code. List the asset, jurisdiction, investor type, license touchpoints, custody model, token standard, transfer rules, and audit evidence. If that map has gaps, the product is not ready for mainnet or clients. For professionals who also need to understand how emerging technologies connect with market positioning, a Marketing Certification can complement technical and compliance-focused expertise.
FAQs
1. What is RWA tokenization compliance?
RWA tokenization compliance refers to the legal, regulatory, and operational requirements involved in converting real-world assets into blockchain-based tokens. It can include securities laws, KYC/AML requirements, investor protection, taxation, custody, privacy, and reporting obligations.
2. Why is compliance important in RWA tokenization?
Compliance helps ensure that tokenized assets are legally structured, properly issued, transparently managed, and distributed to eligible participants. It also helps reduce regulatory, financial, operational, and reputational risks.
3. What legal requirements apply to RWA tokenization?
Requirements vary based on the asset, token structure, jurisdiction, and intended investors. They may include securities regulations, property laws, financial-services regulations, KYC/AML rules, licensing, tax requirements, custody standards, and disclosure obligations.
4. Are all RWA tokens considered securities?
No. An RWA token may represent a security, commodity interest, fund interest, ownership claim, contractual right, or another type of asset or economic interest. Its classification depends on its underlying rights and applicable laws.
5. What is KYC in RWA tokenization?
Know Your Customer (KYC) involves verifying the identity and relevant information of investors or participants. KYC can help determine whether an individual or organization is legally eligible to purchase, hold, or transfer a particular RWA token.
6. How does AML apply to tokenized real-world assets?
Anti-Money Laundering (AML) controls help identify and mitigate potential financial-crime risks. Platforms may use identity verification, sanctions screening, transaction monitoring, risk assessments, and suspicious-activity reporting.
7. What is investor eligibility in RWA tokenization?
Investor eligibility determines who can legally participate in a tokenized asset offering. Depending on the jurisdiction and product, restrictions may apply based on investor status, location, financial qualifications, or other regulatory criteria.
8. How can smart contracts support RWA compliance?
Smart contracts can automate compliance-related rules such as wallet whitelisting, transfer restrictions, investor eligibility, holding limits, payment conditions, and redemption requirements. They support compliance but do not replace legal oversight.
9. What is a compliant token transfer?
A compliant token transfer follows the applicable laws, investor restrictions, KYC/AML requirements, contractual terms, and platform rules. Simply recording a transaction on a blockchain does not make the transaction legally compliant.
10. Why is asset verification important for RWA compliance?
Asset verification helps establish that the underlying asset exists, is properly owned or controlled, and corresponds to the rights represented by the token. Documentation, audits, custodial records, valuations, and independent verification can strengthen this process.
11. How should businesses verify an asset before tokenization?
Businesses should conduct thorough due diligence by reviewing ownership documents, registrations, liens, existing claims, valuation records, custody arrangements, and legal rights before issuing tokens linked to an asset.
12. What compliance controls should an RWA tokenization platform use?
Common controls include KYC/AML screening, investor onboarding, wallet whitelisting, transaction monitoring, access controls, asset verification, cybersecurity measures, audit trails, regulatory reporting, and periodic compliance reviews.
13. What disclosures are important for tokenized assets?
Depending on the product, investors may need clear information about the underlying asset, token rights, ownership structure, valuation, fees, risks, liquidity, redemption terms, conflicts of interest, and regulatory status.
14. How does custody affect RWA tokenization compliance?
Custody determines how the underlying asset is held and protected. Effective arrangements should clearly establish custodian responsibilities, asset segregation, access controls, recordkeeping, and procedures for redemption or transfer.
15. What tax considerations apply to RWA tokenization?
Tax treatment varies by jurisdiction and asset type. Businesses and investors may need to consider capital gains, income taxes, withholding taxes, transaction taxes, reporting requirements, and the tax treatment of token transfers or distributions.
16. How does data privacy apply to RWA tokenization?
Tokenization platforms should carefully manage personal information, particularly when using public blockchains. Common approaches include keeping sensitive identity information off-chain, encryption, access controls, and data minimization.
17. What are the biggest compliance risks in RWA tokenization?
Major risks include incorrect legal classification, inadequate KYC/AML controls, inaccurate asset records, unauthorized transfers, weak investor disclosures, custody failures, privacy violations, regulatory changes, and non-compliant cross-border transactions.
18. What are the best practices for RWA tokenization compliance?
Best practices include determining legal classification before issuance, documenting asset ownership, implementing strong KYC/AML procedures, restricting transfers when required, maintaining accurate records, conducting regular audits, protecting investor data, and monitoring regulatory developments.
19. How can businesses maintain compliance after issuing RWA tokens?
Compliance should continue throughout the asset's lifecycle. Businesses should regularly review investor eligibility, asset status, transaction activity, regulatory requirements, disclosures, smart-contract controls, custody arrangements, and reporting obligations.
20. What is the future of RWA tokenization compliance?
RWA compliance is likely to become increasingly automated and integrated directly into tokenization infrastructure. Digital identity, permissioned wallets, programmable compliance, automated monitoring, and regulatory technology could make it easier for businesses to manage tokenized assets while meeting evolving legal requirements.
Related Articles
View All
Digital Assets
How AI in RWA Tokenization Is Changing Valuation, Compliance, and Risk
AI in RWA tokenization is reshaping valuation, compliance, surveillance, and risk analytics for tokenized real-world assets.

Digital Assets
Best RWA Tokenization Platforms: Features, Use Cases, and Selection Criteria
Compare the best RWA tokenization platforms, including Securitize, Ondo Finance, Franklin Templeton, Centrifuge, Maple, Paxos, Tether, and Tokeny.

Digital Assets
RWA Tokenization and KYC/AML: Identity, Compliance, and Investor Protection
RWA tokenization is moving into regulated markets. Learn how KYC/AML, wallet whitelists, travel rule workflows, and disclosures protect investors.
Trending Articles
The Role of Blockchain in Ethical AI Development
How blockchain technology is being used to promote transparency and accountability in artificial intelligence systems.

Top 5 DeFi Platforms
Explore the leading decentralized finance platforms and what makes each one unique in the evolving DeFi landscape.
Can DeFi 2.0 Bridge the Gap Between Traditional and Decentralized Finance?
The next generation of DeFi protocols aims to connect traditional banking with decentralized finance ecosystems.