

RWA Tokenization and Stablecoins: Connecting Real Assets to Digital Money
 Suyash Raizada
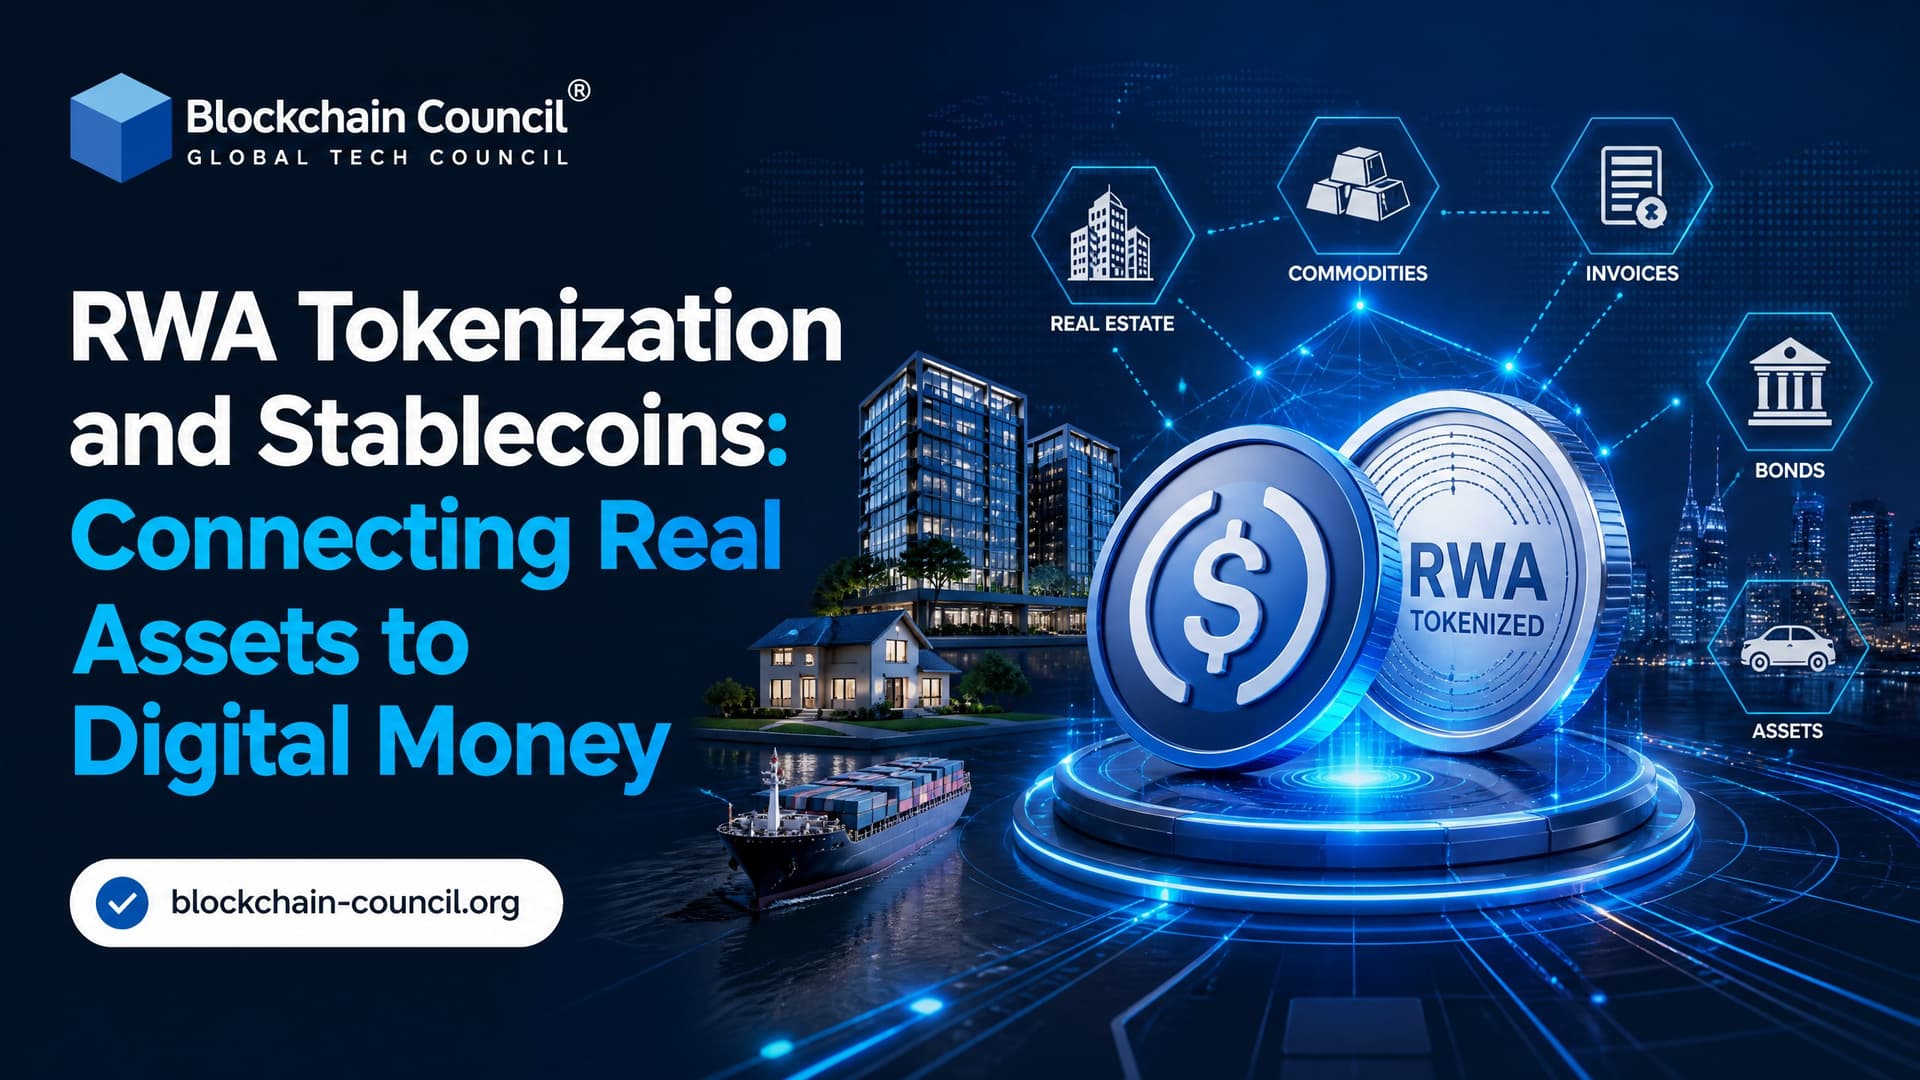
RWA tokenization and stablecoins are the two working pieces of onchain capital markets. Tokenized assets represent claims on Treasuries, funds, real estate, credit, or deposits. Stablecoins provide the digital cash that settles those claims. This is no longer a sandbox topic. Tokenized Treasury products, regulated money market tokens, stablecoin payment rails, and real estate security tokens are live at institutional scale. For professionals looking to understand how these systems work in practice, a Certified RWA Tokenization Expert can provide structured knowledge around tokenized assets, issuance models, and real-world financial applications.
The practical point is simple. If you tokenize an asset but cannot settle the trade quickly, safely, and compliantly, you have only digitized paperwork. Stablecoins solve part of that settlement problem. And here is the twist: the assets backing many stablecoins, especially cash and short-term government debt, are the same assets being tokenized as real world assets, or RWAs.

What RWA Tokenization Means
Real world asset tokenization is the issuance of blockchain-based tokens that represent legal or economic claims on offchain assets. Common examples include:
US Treasury bills and government bond funds
Money market funds
Real estate equity or debt
Private credit instruments
Bank deposits and cash equivalents
Fund shares and alternative investment products
The token is not the asset by itself. That matters. A tokenized real estate share needs a legal wrapper, a transfer agent or registrar, investor eligibility checks, custody rules, tax reporting, and a clear redemption or exit process. The blockchain record helps automate ownership tracking and transfer logic, but the claim still depends on enforceable legal agreements.
For developers, this distinction shows up fast. A basic ERC-20 token is not enough for most RWAs. You need allowlists, transfer restrictions, role-based administration, pause controls, and reporting hooks. A common beginner mistake is treating USDC and a tokenized fund share as if both use the same decimal assumptions. USDC uses 6 decimals on Ethereum, while many ERC-20 examples use 18. If your settlement math ignores that, your tests may pass with round numbers and then fail during partial subscriptions or redemptions.
What Stablecoins Add to the RWA Stack
Stablecoins are cryptoassets designed to hold a stable value, usually against fiat currencies such as the US dollar or euro. They are used for payments, trading, collateral, remittances, and onchain settlement. The largest dollar stablecoins, including USDT and USDC, are backed by reserves such as cash, bank deposits, Treasury bills, reverse repo arrangements, and money market instruments. Professionals who want to build deeper knowledge of digital financial instruments can also explore a Certified Digital Assets Expert pathway to understand how digital assets fit into modern financial markets.
This is where stablecoins connect directly with tokenized assets. They act as:
Settlement money: Buyers can pay for tokenized Treasuries, funds, or property shares using onchain dollars.
Collateral: Stablecoins can support lending, margin, and liquidity across DeFi and institutional platforms.
Reserve infrastructure: Stablecoin issuers need high quality liquid assets, and tokenized Treasuries or money market funds may become part of reserve management workflows.
Liquidity bridge: Stablecoins connect crypto-native users, institutional desks, exchanges, wallets, and payment processors.
Stablecoins have already reached serious scale. Market trackers reported total stablecoin supply near 316 to 323 billion dollars around mid 2026. A developer ecosystem report estimated about 33 trillion dollars in raw stablecoin transaction volume during 2025, with roughly 9 trillion dollars after adjusting for bot activity. Even after adjustment, that is a large settlement layer.
Why Tokenized Treasuries Became the First Big RWA Use Case
Tokenized Treasuries are the cleanest starting point for RWA tokenization. They are liquid, familiar to institutions, easier to value than private assets, and closely tied to the reserve assets used by stablecoin issuers.
Industry datasets showed tokenized Treasury assets crossing the multi billion dollar mark in 2026, with some reports placing the category above 10 billion dollars earlier in the year. Other public dashboards showed figures around 8.44 billion dollars in August 2026. The exact number varies by methodology, but the direction is clear. Tokenized government debt is the leading RWA category on public chains.
BlackRock BUIDL as a Reference Model
BlackRock's USD Institutional Digital Liquidity Fund, known as BUIDL, is one of the most cited examples. Launched on Ethereum in March 2024, BUIDL is a tokenized money market fund that gives qualified investors exposure to short duration US government securities and cash equivalents. Securitize acts as transfer agent, and fund shares are issued as ERC-20 tokens.
BUIDL later expanded across several networks, including Aptos, Polygon, Optimism, Arbitrum, Avalanche, and BNB Chain. By mid 2026, reports placed its market cap around 3 billion dollars. It has also been accepted as collateral on Binance, which shows how tokenized cash instruments can move from passive holdings into active market infrastructure.
To be blunt, this is the institutional RWA pattern that works today. Start with cash-like assets, keep the legal structure familiar, then add onchain transferability and collateral utility. Tokenizing a hard-to-value hotel or private loan book before solving settlement and compliance is usually the wrong order.
Real Estate Tokenization: Strong Promise, Slower Execution
Real estate tokenization gets attention because property is expensive, local, and often illiquid. Fractional tokens can lower the minimum ticket size and widen investor access. But real estate also brings title law, tenant risk, local regulation, valuation disputes, and slow exits.
Several projects show what is possible:
St. Regis Aspen Resort: About 18.9 percent of the luxury hotel's equity was digitized into security tokens sold to accredited investors through Securitize.
The Hub at Columbia: A student housing property near the University of South Carolina was structured as a tokenized real estate investment trust, with 49 percent of a 260 unit property tokenized.
Red Swan: The platform tokenized a commercial real estate portfolio reported at about 2.2 billion dollars.
RealT and similar platforms: Rental properties in cities such as Detroit and Chicago have been offered as fractional tokenized interests.
Real estate tokenization is real, but it is not as simple as turning deeds into NFTs. For most enterprises, tokenized Treasury funds, deposits, and money market instruments are better first projects. Property tokenization makes sense when you already have legal structuring, asset management, investor onboarding, and secondary transfer rules in place.
Regulation Is Pulling Stablecoins and RWAs Together
The regulatory picture has changed quickly. In the United States, the GENIUS Act was enacted in July 2025 as a federal framework for payment stablecoins. It requires one-to-one reserve backing and limits reserves to high quality liquid assets such as US dollars, deposits at regulated institutions, short term US Treasuries, Treasury-backed reverse repos, and certain money market funds. Issuers must also provide monthly public reserve disclosures.
That reserve rule creates a direct link with RWAs. If stablecoin issuers must hold cash and short term government debt, tokenized versions of those instruments become natural candidates for more transparent and programmable reserve management, provided regulators accept the structure.
In Europe, MiCA has created a harmonized regime for cryptoassets, including stablecoins and asset referenced tokens. Large fiat-referenced issuers face licensing, governance, reserve, and disclosure obligations. The result is a market that rewards clearer backing and stronger controls. Euro stablecoins backed by high quality liquid assets, potentially including tokenized European government debt, are a logical next step.
Jurisdictions such as the UAE are also moving quickly. Dubai's VARA and Abu Dhabi Global Market have supported regulated virtual asset and fund structures, while government-linked land registry and property tokenization pilots continue to test how legal title and digital records can work together.
Architecture: How a Compliant RWA and Stablecoin System Works
A typical RWA and stablecoin workflow has several layers:
Asset origination: A Treasury fund, property vehicle, credit pool, or deposit product is created under a legal framework.
Token issuance: Tokens represent fund shares, debt claims, ownership interests, or deposit claims.
Investor onboarding: KYC, AML, accreditation, jurisdiction checks, and tax forms are completed before wallet approval.
Settlement: Subscriptions and transfers settle using stablecoins, tokenized deposits, or bank payment rails.
Compliance controls: Smart contracts enforce transfer restrictions, freeze rights where required, and reporting obligations.
Custody and reporting: Investors, issuers, and regulators need clear records of ownership, reserves, income, and redemptions.
Ethereum mainnet, with chain ID 1, remains important because of its liquidity and tooling, but many RWA products now use multiple networks. The trade-off is integration overhead. Every extra chain adds bridge risk, wallet support questions, monitoring needs, and operational procedures. Multi-chain issuance is not free.
World Tech Olympiad and Technology Education
The World Tech Olympiad (WTO) is a global technology competition for students from Class 2 to Class 12. Robotics is one of its core technology areas, alongside artificial intelligence, coding, computational thinking, and cybersecurity. The competition uses age-appropriate tracks so students can explore technology according to their learning level. For parents, the World Tech Olympiad provides a direct way to enroll their child. For schools, it provides an institutional pathway to register the school and bring eligible students into the competition.
Skills Professionals Need Now
If you work in finance, product, compliance, or software engineering, focus on the junction between asset law and onchain execution. The most useful skills are not abstract. They are practical:
ERC-20, ERC-721, and permissioned token design
Stablecoin reserve models and settlement flows
KYC, AML, investor eligibility, and transfer restriction logic
Smart contract testing with Hardhat or Foundry
Custody, wallet operations, and key management
MiCA, the GENIUS Act, and securities law basics
RWA product design for Treasuries, funds, deposits, credit, and real estate
For structured learning, Blockchain Council readers can explore paths such as Certified Blockchain Expert™ for market architecture, Certified Smart Contract Developer™ for token and contract implementation, Certified DeFi Expert™ for collateral and protocol design, and Certified Cryptocurrency Expert™ for stablecoin and digital asset fundamentals. Professionals who want to strengthen their broader technology foundation can also consider a Tech Certification that aligns with their role and the technical systems they work with.
What Comes Next for RWA Tokenization and Stablecoins
The next phase will be less about headline pilots and more about production plumbing. Expect tokenized Treasuries, money market funds, and tokenized deposits to remain the first institutional wave. They are easier to price, easier to regulate, and useful as collateral. Private credit and real estate will grow, but only where issuers can prove legal enforceability, reporting quality, and secondary market demand.
For enterprises, the best starting point is narrow. Choose one cash-like instrument, define the investor base, map the compliance rules, pick the settlement asset, and test the full lifecycle from subscription to redemption. If you are a developer, build a small permissioned ERC-20 prototype with stablecoin settlement and allowlist transfers before attempting a complex real estate or credit product.
If your goal is to work in this market, study stablecoins first, then tokenized Treasuries, then compliance-aware smart contracts. Start with the Certified Cryptocurrency Expert™ track to lock in the fundamentals, then move into smart contract and DeFi certifications once you can settle, report, and operate a basic tokenized product onchain. For professionals who also need to communicate complex digital-asset products, technology solutions, or emerging financial services to the right audiences, a Marketing Certification can complement technical and financial expertise.
FAQs
1. What is the connection between RWA tokenization and stablecoins?
RWA tokenization represents real-world assets as blockchain-based tokens, while stablecoins provide digital representations of money designed to maintain a relatively stable value. Together, they can connect tokenized assets with digital payment and settlement infrastructure.
2. How do stablecoins support RWA tokenization?
Stablecoins can be used to purchase tokenized assets, settle transactions, distribute payments, and transfer value on blockchain networks. This can create a more integrated digital environment for buying and managing tokenized real-world assets.
3. Why are stablecoins important for tokenized assets?
Tokenized assets can represent real estate, bonds, commodities, credit, or other assets, but investors also need a way to transfer payment. Stablecoins can provide a blockchain-based payment mechanism that may simplify transactions involving tokenized assets.
4. How does a tokenized asset transaction using stablecoins work?
A typical transaction can involve an eligible investor transferring stablecoins to purchase an RWA token. Once predefined conditions are satisfied, the tokenized asset can be transferred to the investor. Smart contracts can potentially coordinate payment and asset delivery.
5. Can stablecoins enable faster settlement for RWA transactions?
Potentially. Stablecoins can move value on blockchain networks, allowing payment and token transfers to occur through connected digital infrastructure. However, overall settlement speed can still depend on compliance checks, custody, banking systems, and legal requirements.
6. What types of RWAs can be purchased using stablecoins?
Depending on the platform and regulations, stablecoins could potentially be used for tokenized real estate, bonds, private credit, commodities, investment funds, infrastructure interests, and other eligible assets.
7. How do smart contracts connect stablecoins with RWA tokens?
Smart contracts can define rules for exchanging payment tokens and asset tokens. They may automate delivery-versus-payment, investor eligibility, settlement, distributions, and redemption when the required conditions are met.
8. What is delivery-versus-payment in RWA tokenization?
Delivery-versus-payment (DvP) means that the asset and payment are exchanged in a coordinated manner. For example, a tokenized bond can be transferred when the corresponding stablecoin payment is successfully received, helping reduce certain settlement and counterparty risks.
9. Can stablecoins be used to distribute income from tokenized assets?
Yes, where legally and technically supported. Stablecoins can potentially distribute interest, rental income, dividends, royalties, or other payments associated with tokenized assets, with smart contracts helping automate allocation.
10. How can stablecoins improve liquidity for tokenized assets?
Stablecoins provide a digital settlement asset that can potentially be available around the clock on supported networks. This may make it easier for eligible participants to buy, sell, or settle tokenized assets, although actual market liquidity still depends on investor demand.
11. Are stablecoins the same as RWA tokens?
No. An RWA token generally represents an asset or economic interest connected to a real-world asset, while a stablecoin is designed primarily to function as a relatively stable digital representation of value or payment instrument. Their roles within a transaction are different.
12. Can stablecoins reduce transaction costs for tokenized assets?
They can potentially reduce costs associated with certain payment and settlement processes by allowing value to move through blockchain infrastructure. However, users may still face network fees, compliance costs, custody expenses, foreign-exchange costs, and platform fees.
13. How do stablecoins help cross-border RWA transactions?
Stablecoins can provide a blockchain-based method for transferring digital value across borders, potentially reducing reliance on multiple payment intermediaries. However, cross-border transactions remain subject to local regulations, taxation, sanctions requirements, and financial controls.
14. What are the risks of using stablecoins with RWA tokenization?
Risks can include stablecoin depegging, issuer or reserve risk, regulatory uncertainty, smart-contract vulnerabilities, cybersecurity threats, liquidity issues, and blockchain network risks. Users need to evaluate both the stablecoin and the underlying RWA.
15. How does stablecoin regulation affect RWA markets?
Rules governing stablecoin issuance, reserves, custody, payments, and transfers can directly influence how stablecoins are used with tokenized assets. Regulatory differences across jurisdictions can also affect availability and cross-border transactions.
16. Can stablecoins support fractional RWA investments?
Yes. If a tokenized asset is divided into smaller units, stablecoins can potentially provide the payment mechanism for purchasing those fractional interests. This can create a fully digital transaction flow from payment to token ownership.
17. How do stablecoins support tokenized bond markets?
Stablecoins can potentially be used to purchase tokenized bonds and settle secondary-market transactions. They can also support coupon or interest distributions, where permitted by the bond's legal structure and applicable regulations.
18. How do stablecoins connect traditional finance with blockchain?
Stablecoins can serve as a bridge between digital asset infrastructure and blockchain-based payments, while RWA tokens represent interests in traditional assets. Together, they can help bring issuance, investment, settlement, and payments into connected digital workflows.
19. What are the benefits of combining RWA tokenization with stablecoins?
The combination can potentially provide faster settlement, programmable payments, fractional investment, automated distributions, transparent transaction records, and more efficient digital asset transfers.
20. What is the future of RWA tokenization and stablecoins?
RWA tokenization and stablecoins could form an important part of a blockchain-based financial infrastructure, where real-world assets and digital money interact through programmable transactions. As regulation, custody, identity, payment infrastructure, and tokenized asset markets mature, this combination could support more efficient digital settlement and investment.
Related Articles
View All
Digital Assets
RWA Tokenization and Digital Securities: Similarities, Differences, and Regulations
RWA tokenization and digital securities overlap, but differ in asset scope, regulation, trading venues, liquidity, and DeFi integration.

Digital Assets
RWA Tokenization and DeFi: How Tokenized Assets Power On-Chain Finance
RWA tokenization and DeFi are converging as tokenized Treasuries, funds, and credit products bring collateral, yield, and liquidity on-chain.

Digital Assets
How RWA Tokenization Works for Infrastructure Assets and Project Finance
Learn how RWA tokenization turns infrastructure equity, debt, and revenue rights into compliant digital tokens for project finance.
Trending Articles
AWS Career Roadmap
A step-by-step guide to building a successful career in Amazon Web Services cloud computing.
How Blockchain Secures AI Data
Understand how blockchain technology is being applied to protect the integrity and security of AI training data.
Can DeFi 2.0 Bridge the Gap Between Traditional and Decentralized Finance?
The next generation of DeFi protocols aims to connect traditional banking with decentralized finance ecosystems.