

CBDC Interoperability Explained: Connecting Banks, Wallets, and Blockchains
 Suyash Raizada
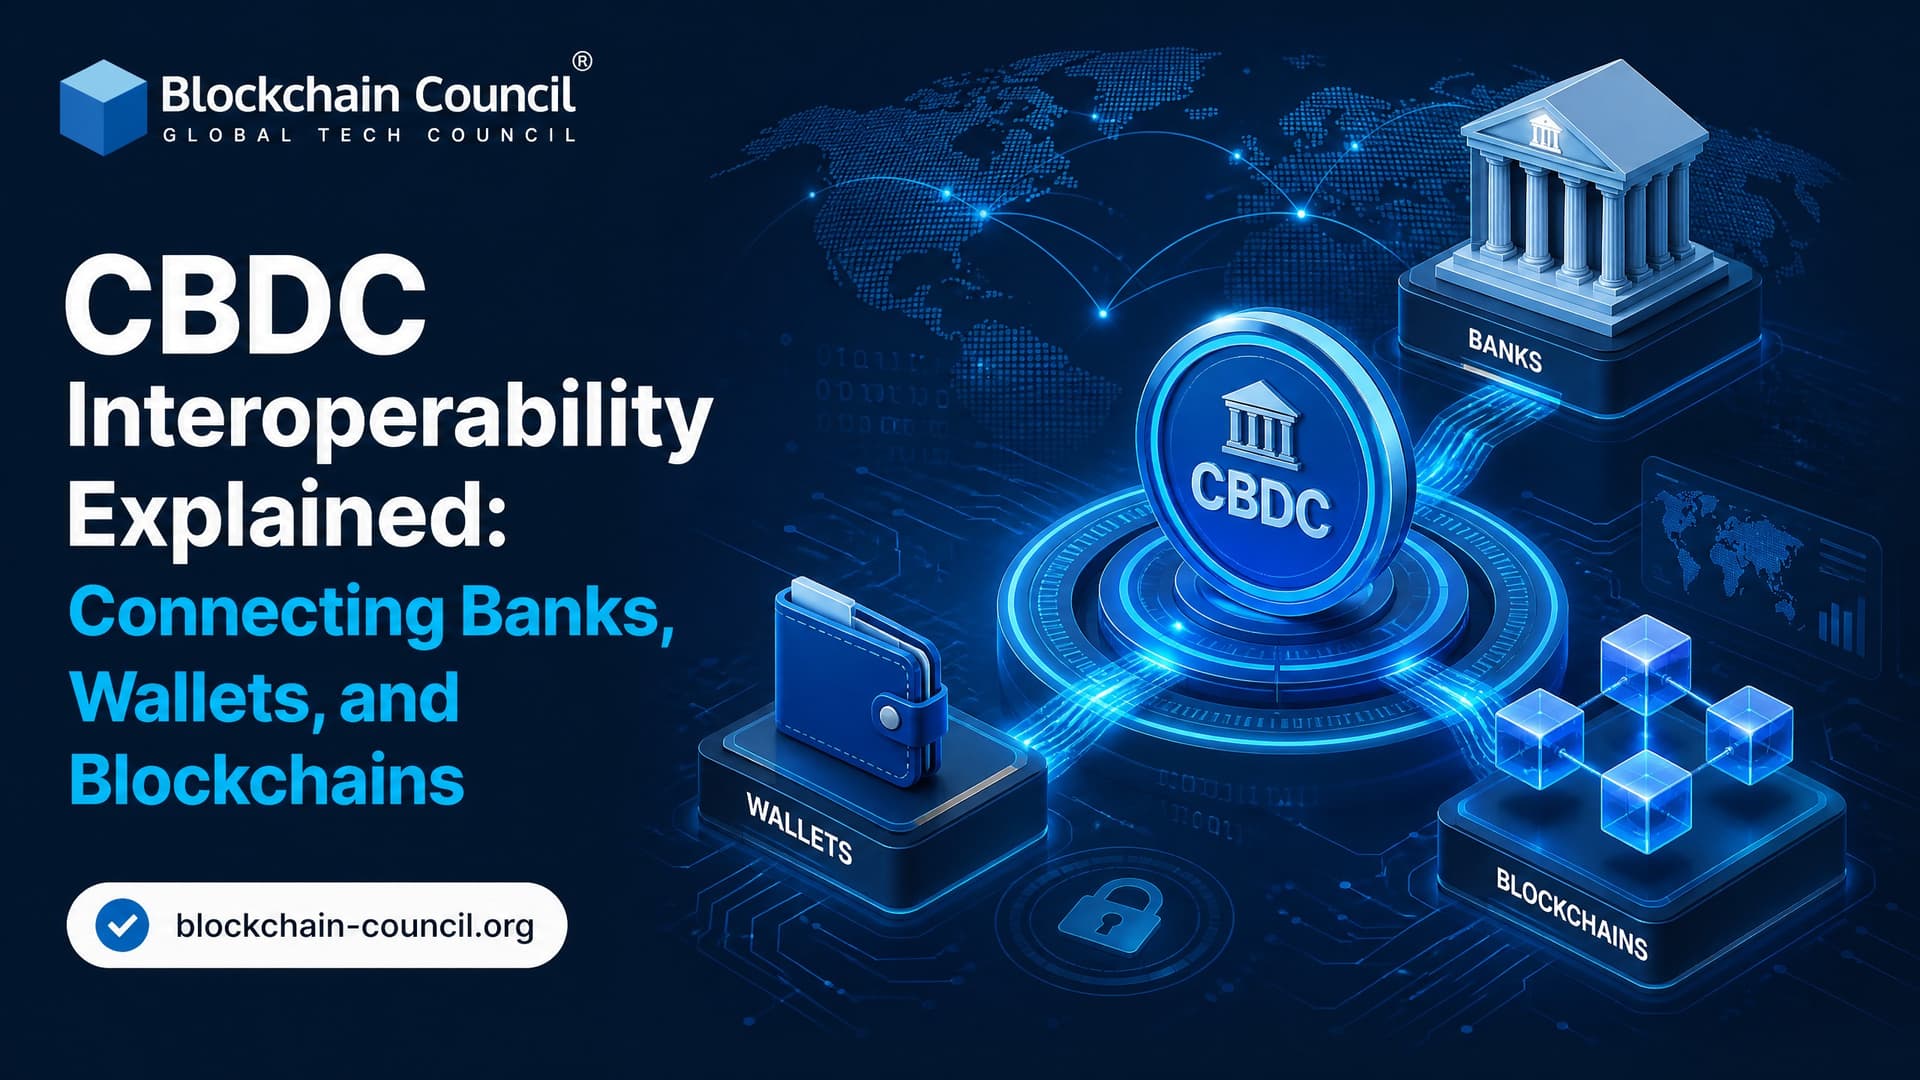
CBDC interoperability is the ability of central bank digital currency systems to work with banks, retail wallets, payment networks, and blockchain platforms without trapping value in isolated systems. That sounds simple. It is not. The hard part is making legal finality, identity, compliance, liquidity, and data standards line up across systems built by different central banks, vendors, and market participants.
The topic has moved from policy papers to live pilots. The BIS, IMF, World Economic Forum, SWIFT, HKMA, and several central banks are now testing how CBDCs can connect to RTGS systems, fast payment rails, FX markets, and tokenized assets. If you work in payments, digital assets, banking technology, or blockchain infrastructure, CBDC interoperability is a core design question now, not a side topic. It is also the kind of topic where a structured Certified Central Bank Digital Currency (CBDC) Expert foundation pays off, since interoperability design touches nearly every part of a typical CBDC curriculum at once.

What CBDC Interoperability Means
CBDC interoperability means that one CBDC system can communicate, transact, and settle with another system. That other system may be a domestic payment rail, a commercial bank ledger, a retail wallet, a foreign CBDC platform, or a blockchain-based securities network.
In practice, it covers four layers:
Domestic payment integration: CBDCs connect with RTGS, instant payment systems, card rails, and bank account infrastructure.
Cross-border CBDC links: Multiple central bank digital currencies support payment versus payment, also called PvP, for FX settlement.
Bank and wallet access: Commercial banks, payment service providers, and wallet operators use shared standards for identity, messaging, security, and compliance.
Blockchain and tokenized asset settlement: CBDCs support delivery versus payment, or DvP, for securities, tokenized deposits, trade finance, and other digital assets.
The BIS has argued that CBDCs without interoperability could create new digital islands. That is the right warning. A retail CBDC wallet that cannot pay into existing bank and merchant systems is just another closed-loop app. A wholesale CBDC that cannot settle FX or securities against external systems is a narrow settlement tool, not market infrastructure. Because that last layer touches tokenized deposits and digital securities directly, many professionals pair CBDC study with a Certified Digital Assets Expert background to cover the asset side of the interoperability picture too.
Why Banks, Wallets, and Blockchains Need Interoperability
Banks need settlement access and liquidity control
Banks care about final settlement, liquidity, balance sheet treatment, and operational risk. In a wholesale CBDC model, banks may connect as direct participants through nodes, APIs, or regulated gateways. They need to move value between central bank money, commercial bank money, FX positions, and securities accounts.
One practical detail gets missed in high-level diagrams: the message mapping is often where projects stall. In ISO 20022 payment flows, a pacs.009 financial institution credit transfer carries different data expectations than a pacs.008 customer credit transfer. If a CBDC gateway maps the wrong party identifier, or drops a UETR used for payment tracking, reconciliation can fail even though the ledger transaction technically settled. That is not theoretical plumbing. It is the boring, costly part of payment integration.
Wallets need shared identity and payment rules
Retail wallets need common standards for onboarding, identity verification, fraud controls, device security, and transaction messaging. The BIS 2024 survey found that 56 percent of advanced economies and 79 percent of emerging market and developing economies considering retail CBDCs expect them to be interoperable with domestic payment systems.
That matters for adoption. Users should not need to know whether a merchant accepts CBDC, instant payment, or card settlement in the background. The wallet should route the payment, apply compliance checks, and confirm settlement in a format both sides understand.
Blockchains need atomic settlement
Blockchain-based asset markets need trusted cash legs. Tokenized bonds, fund units, invoices, carbon credits, and collateral transfers all need settlement assets that can move with legal finality. CBDCs could provide that cash leg, especially in wholesale markets.
The key mechanism is atomic settlement: both sides of a transaction happen together, or neither happens. For securities, that is DvP. For currency exchange, that is PvP. Smart contracts can coordinate the workflow, but governance and legal finality still come from regulated institutions.
The Three Main Models of CBDC Interoperability
The BIS and IMF often describe three broad models for multi-CBDC interoperability. You will see these models in most serious CBDC architecture discussions.
1. Compatibility model
CBDC systems remain separate, but they use compatible standards. Think shared messaging formats, similar identification schemes, aligned compliance data, and coordinated operating rules.
This is the lowest-disruption model. It fits jurisdictions that want autonomy and limited technical dependency. The trade-off is clear: payments may still pass through multiple intermediaries, so speed and cost gains can be modest.
2. Interlinking model
Separate systems connect through technical interfaces, gateways, or a common clearing mechanism. SWIFT has tested this approach through CBDC sandbox work that linked CBDC networks built on different distributed ledger technologies, including Corda and Quorum, as well as existing RTGS systems.
This model is practical because it does not force every central bank onto one platform. It also fits the real world, where old payment systems rarely disappear quickly. The downside is connector complexity. Gateways must handle message conversion, identity mapping, compliance checks, routing, and settlement status across multiple networks.
3. Single platform model
Multiple CBDCs operate on one shared platform, usually with separate governance rules for each currency. BIS Innovation Hub projects such as mBridge, Dunbar, and Jura have tested this model for wholesale CBDCs.
mBridge is the best-known example. It involves the central banks of Hong Kong SAR, Mainland China, Thailand, and the United Arab Emirates. In a 2022 pilot, 20 commercial banks executed payment and FX PvP transactions for corporate clients using CBDCs issued on the platform. HKMA reported that the trial reduced cross-border payment times from several days to near real time and lowered costs.
This model can deliver strong efficiency gains. It is also politically and legally harder, because shared governance, access rules, data visibility, and dispute processes must be agreed upfront.
Real Use Cases Already Being Tested
CBDC interoperability is not only about sending money from one wallet to another. The higher-value use cases sit in institutional finance and cross-border commerce.
International trade settlement: CBDCs can settle invoices, trade documents, and letters of credit with fewer correspondent banking steps.
FX payment versus payment: Two currencies settle at the same time, reducing Herstatt risk.
Tokenized bond issuance: A bond token and CBDC payment can exchange atomically across borders.
Digital trade workflows: SWIFT sandbox phase 2 tested digital trade, FX settlement, DvP for securities, and a liquidity saving mechanism.
Insurance and wealth product settlement: mBridge participants identified cross-boundary insurance payments and wealth management settlement as possible use cases.
Tokenized institutional cash: Cambridge Centre for Alternative Finance has discussed Fnality, a UK regulated payment operator using an omnibus account at the Bank of England to support tokenized PvP and DvP settlement.
To be blunt, wholesale CBDC interoperability will likely mature before broad retail cross-border CBDC use. The user group is smaller, compliance controls are clearer, and the economic case is stronger in FX, securities, and trade settlement.
Standards That Make CBDC Interoperability Work
Interoperability depends on standards. Not slogans. Actual standards and rulebooks.
ISO 20022: Used for structured financial messaging across payment systems.
BIC and LEI identifiers: Help identify financial institutions and legal entities.
Common identity frameworks: Needed for wallet access, AML/CFT screening, sanctions controls, and transaction limits.
APIs and gateways: Connect CBDC platforms with RTGS systems, fast payment systems, bank ledgers, and blockchain networks.
Legal finality rules: Define when settlement is irrevocable and enforceable.
The World Economic Forum has emphasized that CBDC interoperability is institutional as much as technical. That view is correct. A gateway can translate a message, but it cannot solve a conflict between capital controls, data localization laws, or different definitions of settlement finality. Engineers building these gateways and API layers often benefit from a broader Tech Certification as well, since much of the connector, identity-mapping, and resilience work above is general systems engineering applied to a regulated payments context.
Risks and Design Trade-Offs
Interoperability brings efficiency, but it also concentrates operational and governance risk. You should watch five problem areas.
Cyber and operational resilience: A shared platform or major gateway can become critical infrastructure.
Data privacy: Cross-border CBDC flows may expose sensitive payment and identity data.
Monetary sovereignty: Retail cross-border CBDCs can raise concerns about currency substitution.
Compliance fragmentation: AML/CFT, sanctions, and capital controls vary across jurisdictions.
Liquidity management: Faster settlement can increase intraday liquidity pressure if not designed with liquidity saving tools.
There is no perfect architecture. Compatibility protects autonomy but gives fewer gains. Interlinking is realistic but complex. A single platform is powerful but hard to govern. Pick the model based on the policy goal, not the technology fashion.
What Comes Next for CBDC Interoperability
The direction is clear. Wholesale multi-CBDC platforms will keep advancing. Domestic CBDC designs will increasingly connect to instant payment systems and bank infrastructure. Interoperability gateways will become a specialized market, with one study by Stratistics MRC estimating growth from about 2.2 billion US dollars in 2025 to 14.8 billion US dollars by 2032.
Integration with tokenized assets is the area to watch. If CBDCs can settle tokenized bonds, FX trades, and trade finance obligations with finality, they become part of a broader digital market structure. If they cannot interoperate, they risk becoming isolated central bank databases with limited market impact.
For professionals, the best next step is to build literacy across both payment systems and blockchain architecture. If you are focused on digital assets strategy, explore Blockchain Council resources such as Certified Blockchain Expert™ and Certified Cryptocurrency Expert™. If you build smart contract or tokenization systems, pair that with Certified Blockchain Developer™ or Certified Smart Contract Developer™. CBDC interoperability sits exactly at that intersection: regulated money, programmable assets, and production-grade payment infrastructure. And if your role involves explaining that intersection to banks, regulators, or investors, a Marketing Certification can help you present a genuinely technical topic in a way that non-specialist stakeholders can actually follow.
FAQs
1. What is CBDC interoperability?
CBDC interoperability refers to the ability of different Central Bank Digital Currency systems, banks, wallets, payment networks, and digital platforms to communicate and process transactions with each other. Interoperability allows users to transfer value across different financial systems without unnecessary barriers. For CBDCs to achieve broad adoption, they need to connect smoothly with existing banking infrastructure, fintech platforms, and potentially other digital asset networks.
2. Why is interoperability important for CBDCs?
Interoperability is important because isolated CBDC systems would limit usefulness. If every country, bank, or wallet operates a separate digital currency environment, users may face the same fragmentation problems that exist in traditional payments. Interoperable CBDCs can support faster domestic and international transactions, improve competition, and reduce payment friction. A digital currency that cannot communicate with other systems is basically a very advanced payment island.
3. How do CBDCs connect with commercial banks?
CBDCs can connect with commercial banks through APIs, settlement systems, wallet platforms, and regulated intermediary networks. In many retail CBDC models, banks may distribute wallets, handle customer onboarding, provide compliance services, and support transactions while the central bank manages the underlying digital currency infrastructure. This public-private approach allows CBDCs to benefit from existing banking expertise while maintaining central bank control over monetary issuance.
4. How do CBDCs connect with digital wallets?
CBDCs can connect with digital wallets through secure APIs, authentication systems, and standardized payment protocols. Wallet providers may allow users to store, transfer, and spend CBDCs through mobile applications or other interfaces. Interoperable wallet systems require common standards for identity verification, security, transaction messaging, and settlement. Without these standards, users could end up needing multiple wallets for different CBDCs, which is precisely the kind of digital clutter nobody requested.
5. Can CBDCs work with blockchain networks?
Some CBDC designs may use distributed ledger technology (DLT), while others may use centralized databases or hybrid architectures. CBDCs can potentially interact with blockchain networks through interoperability layers, tokenization platforms, or regulated bridges. However, integration requires careful consideration of security, privacy, scalability, and regulatory compliance. A central bank does not need to use blockchain to create a CBDC, despite the internet's persistent habit of attaching blockchain to every financial innovation discussion.
6. What technologies enable CBDC interoperability?
CBDC interoperability can be supported by technologies such as APIs, distributed ledger protocols, messaging standards, digital identity systems, cryptographic verification, smart contracts, and payment gateways. Cross-border platforms may also use common settlement layers or multi-CBDC infrastructure. The goal is not necessarily to force every system onto one technology but to create reliable communication between different financial environments.
7. How do APIs support CBDC interoperability?
APIs allow different systems to exchange information and perform authorized actions securely. In CBDC ecosystems, APIs can connect central banks, commercial banks, wallet providers, merchants, identity services, and payment platforms. They enable services such as balance checks, payment initiation, transaction verification, and compliance processes. Well-designed APIs are essential because financial systems cannot become interoperable through good intentions and attractive diagrams alone.
8. What is cross-border CBDC interoperability?
Cross-border CBDC interoperability allows digital currencies issued by different countries to interact for international payments. This can support faster settlement, lower costs, improved transparency, and more efficient foreign exchange transactions. Achieving it requires agreements on technical standards, legal frameworks, identity verification, compliance, and data governance. The software connection is usually easier than getting countries to agree on the rules surrounding it.
9. How do multi-CBDC platforms improve interoperability?
Multi-CBDC platforms connect several central bank digital currencies through shared infrastructure. They can enable direct settlement between participating currencies, reduce reliance on traditional intermediaries, and improve cross-border payment efficiency. These platforms may support functions such as foreign exchange settlement, compliance checks, and liquidity management. Their success depends on broad participation and international cooperation.
10. Can CBDCs interact with existing payment systems?
Yes. A successful CBDC system will likely need to integrate with existing payment infrastructure, including bank transfers, card networks, mobile payments, and merchant systems. Integration allows users to adopt CBDCs without completely changing their financial habits. Interoperability with existing systems can also reduce implementation costs and improve adoption. The goal is usually evolution of payments rather than forcing everyone into a completely separate ecosystem.
11. How can CBDC interoperability improve financial inclusion?
Interoperable CBDCs can improve financial inclusion by allowing users to access digital payments across different platforms and providers. People may benefit from lower-cost transfers, wider acceptance, and easier access to government payments. Compatibility with mobile wallets and agent networks can be especially valuable in areas with limited banking infrastructure. Inclusion improves when systems connect easily rather than requiring users to navigate a maze of incompatible services.
12. What are the cybersecurity challenges of CBDC interoperability?
Connecting multiple financial systems creates additional attack surfaces. Risks include API vulnerabilities, identity theft, compromised wallets, unauthorized access, data breaches, and attacks on interoperability bridges. Security measures must include encryption, authentication, access controls, monitoring, vulnerability testing, and incident-response planning. More connections create more possibilities, which is inconveniently true for both financial innovation and the problems that follow it.
13. How does digital identity support CBDC interoperability?
Digital identity allows different CBDC systems and financial institutions to verify users while controlling access to sensitive information. Interoperable identity frameworks can support KYC, AML compliance, fraud prevention, and secure wallet access across platforms. Privacy-preserving identity technologies may allow users to prove necessary information without exposing excessive personal data. Identity systems are therefore a key foundation for trusted digital currency networks.
14. Can CBDCs connect with tokenized assets?
CBDCs could potentially connect with tokenized assets such as digital securities, bonds, and real-world assets. This may enable faster settlement through mechanisms like delivery-versus-payment, where asset transfer and payment occur together. Wholesale CBDCs are particularly relevant for institutional markets because they can provide digital central bank settlement for tokenized financial instruments. This could improve efficiency in capital markets while introducing new regulatory considerations.
15. How do smart contracts support CBDC interoperability?
Smart contracts can automate transactions between compatible digital systems by executing predefined rules. In CBDC environments, they may support automated settlement, conditional payments, trade finance, and programmable financial services. However, many policymakers distinguish between programmable payments and programmable money. Automating transactions can improve efficiency, while restricting how money itself can be used raises broader policy and privacy concerns.
16. What standards are needed for CBDC interoperability?
CBDC interoperability requires standards for transaction messaging, identity verification, cybersecurity, data exchange, settlement processes, and compliance procedures. International organizations, central banks, and financial institutions may need to coordinate these standards. Without common frameworks, different CBDC systems may struggle to communicate effectively. Technical compatibility is only one piece; legal and operational compatibility matter just as much.
17. What challenges prevent global CBDC interoperability?
Challenges include different national regulations, privacy laws, monetary policies, technology choices, cybersecurity requirements, and governance structures. Countries may also have different approaches to sanctions, capital controls, and financial supervision. Political cooperation is therefore essential. The world has successfully connected many networks before, but connecting national financial systems requires more than installing compatible software and hoping everyone agrees.
18. Can CBDCs improve interoperability between banks and fintech companies?
CBDCs could create shared infrastructure that allows banks and fintech companies to build services on top of digital central bank money. Open APIs, standardized access models, and regulated participation could encourage innovation in wallets, payments, lending, and financial applications. However, access rules need to balance competition, security, consumer protection, and operational stability.
19. Will CBDCs create a single global digital currency network?
A single global CBDC network is unlikely in the near future because countries have different monetary, regulatory, and economic priorities. A more realistic outcome is a network of interoperable national CBDCs connected through agreed standards and platforms. Similar to the internet, different systems may remain independent while still communicating effectively. The challenge is building bridges, not convincing every country to move into the same digital apartment building.
20. What is the future of CBDC interoperability?
The future of CBDC interoperability will likely involve stronger connections between central banks, commercial banks, wallets, payment networks, and digital asset platforms. Successful systems will combine technical compatibility with privacy protection, cybersecurity, regulatory cooperation, and user-friendly design. Interoperability may become one of the most important factors determining whether CBDCs remain limited national experiments or become a meaningful part of global digital finance.
Related Articles
View All
Digital Assets
CBDC Governance Explained: Standards, Oversight, and Stakeholder Roles
CBDC governance defines how digital central bank money is issued, supervised, secured, and operated across central banks, banks, PSPs, regulators, and users.

Digital Assets
CBDC vs Mobile Payments: Understanding Wallets, Settlement, and Money Types
CBDC vs mobile payments explained through wallets, settlement, and money types, with real examples from India, China, Nigeria, and the Bahamas.

Digital Assets
CBDC Consultant Career Guide: Advising Banks and Governments
Learn how to become a CBDC consultant, including required skills, client work, CBDC market trends, career paths, and certification options.
Trending Articles
AWS Career Roadmap
A step-by-step guide to building a successful career in Amazon Web Services cloud computing.
Can DeFi 2.0 Bridge the Gap Between Traditional and Decentralized Finance?
The next generation of DeFi protocols aims to connect traditional banking with decentralized finance ecosystems.
Claude AI Tools for Productivity
Discover Claude AI tools for productivity to streamline tasks, manage workflows, and improve efficiency.